Cash Balance & Defined Benefit Plans: Accelerate Retirement Savings & Potentially Reduce Current Taxes
Cash Balance Plans vs Traditional Defined Benefit Plans
Cash Balance and Defined Benefit Plans may provide eligible high-income business owners, physicians, dentists, partners, and professionals with additional tax-deferred retirement contribution capacity beyond a traditional 401(k), depending on age, compensation, employee demographics, plan design, and applicable IRS rules.
Our tailored actuarial designs and turnkey plan administration coordinate with your existing 401(k) and profit
sharing plans to enhance contribution capacity while ensuring full fiduciary compliance.
Maximize Tax Deferral Opportunities
Potentially reduce personal and business tax liability by making substantial pre-tax contributions that exceed typical retirement plan limits, subject to actuarial and IRS rules.
Potential for Compound Growth
Enhance long-term wealth creation through structured compounding and creditor protection within a qualified trust established for your plan.
Custom Actuarial Plan Design
Every plan is custom-designed based on your business demographics, with actuarial calculations determining contributions and limits in compliance with IRS and tax regulations.
The Basics Explained
What Is a Cash Balance Plan?
A Cash Balance Plan is an IRS-approved qualified retirement plan blending features of traditional defined benefit pensions and 401(k) plans. Each participant has an individual hypothetical account credited with employer contributions and a guaranteed interest credit rate. Primarily designed for high-income business owners, partners, and key executives, it allows for pre-tax retirement savings that can exceed limits typical of defined contribution plans. Roney Insurance Solutions, led by John M. Roney, Founder & Principal, provides planning and coordination services working alongside your CPA, actuary/TPA, attorney, and financial advisor as appropriate. Based in Pasadena, California, we also serve clients in other states subject to licensing and product availability.
Allows annual pre-tax contributions potentially exceeding $350,000 depending on age, compensation, and actuarial calculations
Offers significant dollar-for-dollar tax deductions for high-income business owners and executives
Designed to integrate with existing 401(k) and profit sharing plans for enhanced retirement benefits
Features a defined interest crediting rate specified under the plan that provides a defined interest-crediting methodology while the plan remains subject to applicable funding and investment requirements.
Side-by-Side Overview of Retirement Plans
TRADITIONAL 401(k) vs. CASH BALANCE PLAN
Traditional 401(k) Plan
Annual limit: Approximately $23,000 to $30,500 including catch-up contributions
Funding: Employee salary deferrals plus optional employer matching contributions
Risk: Participant bears full market investment risk and volatility
Cash Balance Plan (Hybrid Defined Benefit)
Annual limit: $100,000 to $350,000+ depending on age and actuarial calculations
Funding: 100% employer-funded pre-tax contributions determined by actuarial and IRS rules
Risk: Employer bears interest crediting rate risk, with steady growth potential
Stackable: Can be combined with a 401(k) plan and profit sharing to maximize total annual deductions
What Are the Distinct Features of Each Plan Type?
How Do Cash Balance Plans Differ From Traditional Defined Benefit Plans?
Compare key structural differences to help identify the ideal retirement plan for your business goals, contribution capacity, tax advantages, and administrative preferences.
Cash Balance Plans
A hybrid defined benefit plan featuring participant balances represented as hypothetical accounts, pairing higher potential deduction limits with the transparency and flexibility similar to 401(k) plans.
Individual hypothetical account balance format designed for participant clarity
Annual contribution credits combined with an actuarially determined guaranteed interest credit
Simple rollover options to an IRA or 401(k) upon plan termination or retirement
Flexible plan design that can accommodate different business partner tiers
Traditional Defined Benefit Plans
A traditional defined benefit pension plan using actuarial formulas to calculate lifetime retirement benefits based on years of service and final average compensation, subject to IRS rules and funding limits.
Lifetime monthly annuity benefit expressed as a future retirement income stream
Complex actuarial benefit calculations based on years of service and compensation, which may be difficult for participants to interpret
Mandatory annual funding set by actuarial requirements, resulting in lower short-term variability
Benefits often favor older employees with long tenure approaching retirement
Who May Benefit from Cash Balance or Defined Benefit Plans?
Who Should Consider a Cash Balance or Defined Benefit Plan?
High-income business owners and professionals seeking to accelerate retirement savings beyond traditional 401(k) and profit sharing limits often find defined benefit and cash balance plans to be effective options, recognizing that contribution limits depend on actuarial reviews and IRS rules.
Ideal Candidate Profile & Key Criteria
Business owners, partners, and high-earning independent consultants with consistent, reliable cash flow.
Professionals earning $250,000+ annually who have already maximized their traditional 401(k) contribution limits.
Entrepreneurs seeking substantial annual tax deductions, potentially ranging from $100,000 to $350,000 or more, depending on plan design and actuarial factors.
Established practices and closely held companies with few non-owner employees or favorable employee demographics for defined benefit or cash balance plans.
Principals within 10 to 15 years of retirement aiming to accelerate tax-deferred wealth accumulation, depending on age, compensation, and actuarial assumptions.
Important Qualification Disclaimer
Defined benefit and cash balance plans require committed annual contributions based on actuarial calculations and must be certified by an actuary. These plans are well suited for businesses with stable earnings and consistent profit margins over multiple years.
How Does Tax Planning Work with Cash Balance Plans?
What Are the Potential Tax Advantages of Cash Balance Plans?
Learn how high-earning business owners and partners use structured Cash Balance Plans to potentially reduce current income taxes while accelerating long-term retirement wealth accumulation.
Do You Have High Gross Business Income?
Your business or medical/professional practice generates substantial annual revenue that may be subject to top federal and state income tax brackets.
How Can You Maximize Pre-Tax Contributions?
By pairing a Cash Balance Defined Benefit Plan with your existing 401(k) and Profit Sharing plans, your business may contribute up to $350,000+ annually per owner, depending on age, compensation, actuarial calculations, and IRS limits.
Are Contributions Tax-Deductible?
All employer contributions to Cash Balance Plans are generally recognized as fully tax-deductible business expenses, reducing your adjusted gross income (AGI) for the current tax year according to IRS rules and plan design.
How Are Integrated Plans Designed and Coordinated?
How Does a Cash Balance Plan Work With a 401(k) and Profit Sharing?
By integrating a Defined Benefit Cash Balance Plan—which offers actuarially determined contribution limits—with a traditional 401(k) and Profit Sharing structure, high-earning business owners and partners in Pasadena, California, and other licensed states can potentially increase annual pre-tax deductions well beyond standard limits, subject to IRS rules and plan design.
401(k) Employee Deferrals
Employee pre-tax salary deferrals, including potential catch-up contributions as allowed by IRS limits.
Profit Sharing Plan
Discretionary employer profit contributions designed to maximize defined contribution limits within IRS rules.
Cash Balance Plan
Defined benefit plan tier allowing substantial, age-weighted tax-deductible contributions based on actuarial calculations and IRS regulations.
OUR PROCESS
How Do We Assess Whether a Cash Balance Plan Fits Your Business?
Our comprehensive 5-step actuarial and financial planning roadmap, developed in Pasadena, California, helps business owners maximize tax deductions and wealth accumulation while ensuring compliance with IRS regulations and applicable tax laws, coordinating closely with your CPA, actuary/TPA, attorney, and financial advisor as appropriate.
01
What Is a Census & Demographic Audit?
We review principal compensation, employee headcount, age demographics, and ownership ratios to identify potential contribution room and eligibility for savings, based on actuarial calculations and IRS rules.
02
How Do We Model Tax Impacts & Cash Flow?
We simulate multiple contribution tiers under IRC §§415 and 401(a)(4), estimating potential pre-tax deductions and predictable annual funding commitments determined by actuarial assumptions and IRS limits.
03
What Is Custom Plan Architecture?
We design custom Defined Benefit or Cash Balance plan formulas that may be paired with an existing or enhanced 401(k) Profit Sharing plan, to potentially maximize owner benefits while managing employee costs.
04
What Does Actuarial Certification Involve?
Our credentialed actuaries stress-test nondiscrimination (cross-testing), interest credit rates, and IRS funding corridors to help ensure the plan’s ongoing compliance and financial health.
05
How Do We Handle Implementation & Custody?
We execute IRS-approved plan documents, establish institutional custodial accounts, and align liability-driven investment portfolios to preserve capital, operating primarily in Pasadena, California, with services extended to other states subject to licensing and product availability.
Complimentary actuarial feasibility analysis · Tailored for business owners and partners in Pasadena, California and beyond
Illustrative Example (Not a Guarantee)
How Can a Cash Balance Strategy Impact Your Tax Situation?
This hypothetical example illustrates a $1,000,000 annual earner optimizing pre-tax wealth accumulation through combined plan strategies.
Illustrative Case Study: High-Income Business Owner
Age 52 business owner in Pasadena, California, with $1,000,000 net business income seeking to optimize annual retirement contributions and reduce current marginal tax exposure through actuarially designed plans.
Standard 401(k) With Profit Sharing Overview
Retirement Contribution: $72,000 (maximum 401(k) deferral and employer profit sharing, subject to IRS limits)
Taxable Income Remaining: $931,000
Estimated Tax Bill: Approximately $391,000
Estimated Annual Tax Savings: Approximately $29,000
How Cash Balance and 401(k) Plans Work Together
Combined Contribution: $319,000 ($250,000 cash balance + $72,000 401(k), subject to actuarial and IRS limits)
Taxable Income Remaining: $681,000
Estimated Tax Bill: Approximately $286,000
Estimated Annual Tax Savings: Approximately $134,000
Estimated Result: Potentially over $105,000 in immediate annual tax deferral, combined with accelerated wealth growth in a protected, creditor-shielded defined benefit account.
*For illustration only. Actual allowable contributions and potential tax savings depend on age, compensation, business structure, plan design,
actuarial calculations, and applicable IRS/tax rules..Hypothetical example for educational purposes only. Actual contribution amounts, deductions,
and tax results vary based on individual circumstances, plan design, actuarial calculations, business structure, and applicable tax law.
What Should You Watch For?
Common Cash Balance Plan Planning Mistakes
Avoid common structural and actuarial errors that can create unexpected funding obligations or risk noncompliance with tax regulations.
How Can Asset Volatility Affect Funding?
Using defined benefit assets like standard equities invites volatility, possibly requiring emergency catch-up contributions during market declines.
What Are the Pitfalls of Rigid Contribution Schedules?
Lack of integration with safe-harbor 401(k) options reduces plan design flexibility and may force rigid owner contribution commitments.
What Are the Consequences of Overlooking Combined Testing?
Skipping essential demographic cross-testing may lead to failed IRS compliance tests and jeopardize tax advantages.
How Does Asset Allocation Impact Plan Stability?
Managing defined benefit pools like volatile equities risks sharp market swings that can cause urgent and expensive top-up funding obligations.
Why Are Rigid Contribution Schedules a Concern?
Excluding safe-harbor 401(k) plans from integration limits owner flexibility and may result in fixed contribution requirements despite business seasonality.
What Happens When Combined Testing Is Ignored?
Failing to perform required non-discrimination tests across demographic groups risks loss of plan tax benefits and IRS sanctions.
What Causes Volatile Asset Allocation Problems?
Treating defined benefit funds like standard equity investments can cause significant market volatility, which may require emergency additional contributions in down years.
How Can Contribution Schedules Become Restrictive?
Not coordinating safe-harbor 401(k) plans with cash balance or defined benefit plans may reduce contribution flexibility, potentially locking owners into rigid funding schedules during revenue fluctuations.
What Are the Risks of Overlooking Combined Testing?
Neglecting required cross-testing and non-discrimination calculations across owner and employee demographics can lead to disallowed deductions and potential IRS penalties.
Why Choose Roney Insurance Solutions?
Comprehensive Planning in Pasadena, California, with Coordinated Execution
Integrating advanced wealth preservation strategies with coordinated, multi-disciplinary execution to help protect your legacy for future generations.
Fiduciary Commitment
Independent, objective advice delivered with your personal and business goals as the central focus.
Tax-Efficient Planning
Custom insurance structures designed to protect substantial assets and reduce estate transfer tax exposure.
Institutional Partnerships
Established direct relationships with leading carriers, providing strong underwriting support and capacity for high-value cases.
Advisory Collaboration
Seamless coordination with your CPA, estate attorney, actuary/TPA, financial advisor, and family office to ensure aligned plan execution.
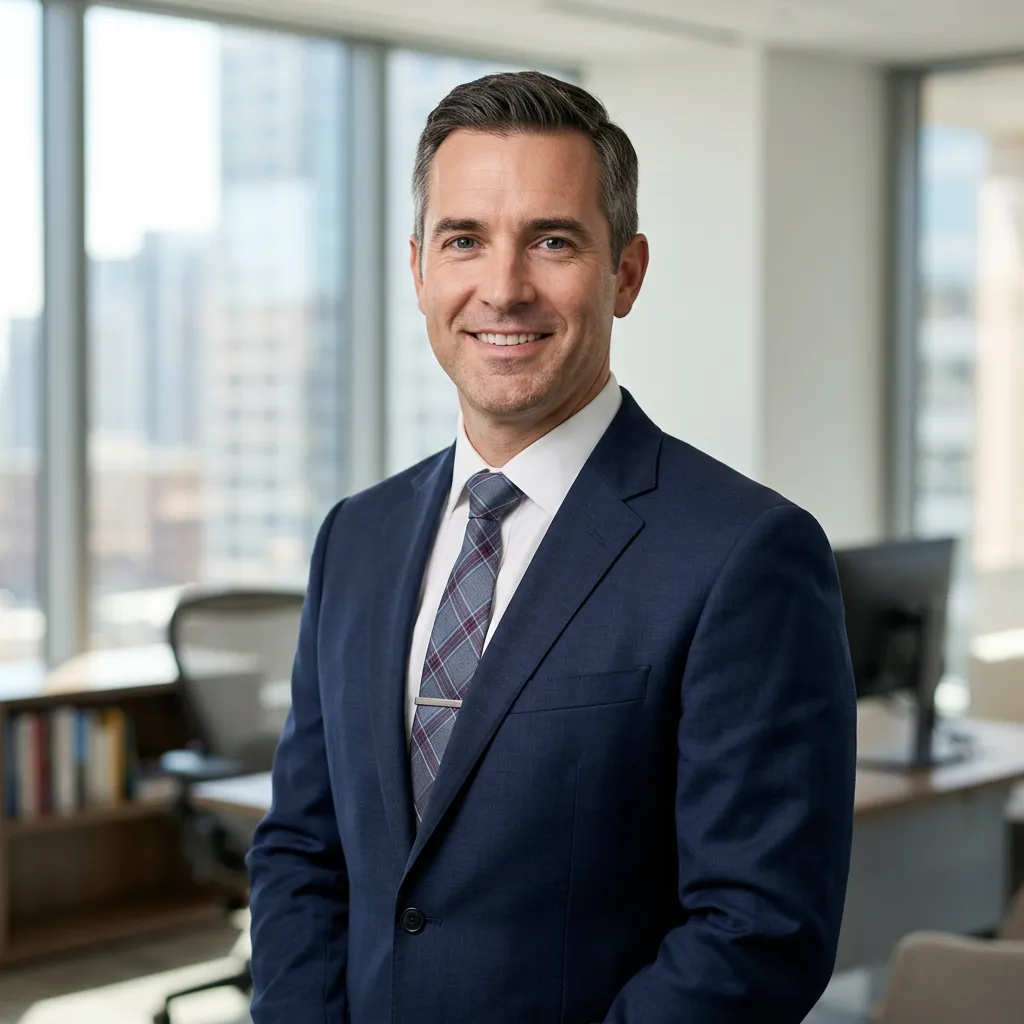
John M. Roney
CFP®, CLU® | Founder & Principal of Roney Insurance Solutions
With over twenty years of experience guiding affluent families, business principals, and private foundations, John M. Roney, Founder & Principal of Roney Insurance Solutions, designs high-limit life insurance portfolios with meticulous care. His consultative approach ensures each policy supports the client's comprehensive wealth transfer and liquidity objectives.
Frequently Asked Questions About Cash Balance Plans
Cash Balance, Defined Benefit, 401(k), and Profit Sharing Plan FAQs
Clear explanations on contribution limits, plan combination strategies, tax deductibility, and compliance for high-income professionals and business owners in Pasadena, California, with service extended to other states subject to licensing.
What distinguishes a Cash Balance Plan from a traditional Defined Benefit Plan?
Both are IRS-qualified defined benefit plans offering substantial pre-tax savings. A Cash Balance Plan presents benefits as an individual hypothetical account balance with an interest credit rate, which is generally easier for partners and key employees to understand than traditional monthly annuity pension calculations.
Who may benefit most from adopting a Cash Balance Plan?
High-earning business owners, medical and law practices, and independent consultants in Pasadena, California—and other states as licensed—who generate consistent annual profits and aim to accelerate retirement savings typically over 5 to 10 years may benefit the most. Cash Balance Plans enable tax-deductible contributions that can exceed standard 401(k) limits depending on actuarial calculations and IRS rules.
Can a Cash Balance Plan be combined with an existing 401(k) and Profit Sharing Plan?
Yes, pairing a Cash Balance Plan with a Safe Harbor 401(k) and Profit Sharing Plan is a common strategy. This integrated design allows business owners to potentially maximize combined contributions—often exceeding $300,000 per year—depending on owner age, compensation, plan design, and employee demographics.
How are annual funding requirements determined, and is there flexibility?
An enrolled actuary calculates required contribution ranges considering participant age, compensation history, and plan provisions, in line with applicable IRS and tax regulations. Some modern plan designs incorporate dynamic contribution ranges to offer practical flexibility during revenue fluctuations.
What happens to accumulated plan assets when the owner retires or sells the company?
At retirement, plan termination, or business sale, vested account balances may be rolled over tax-free into a traditional IRA or another qualified plan—preserving tax deferral and compounding without immediate tax consequences.
Is a Cash Balance Plan Strategy Suitable for Your Business Needs?
How Can You Maximize Your Tax Savings?
Learn how high-income business owners and partners in Pasadena, California, and select other states can potentially reduce annual tax liabilities while accelerating personal retirement wealth, through actuarially calculated contributions under Cash Balance Plans coordinated with your CPA, actuary, attorney, and financial advisor.
Custom Plan Design • No-Obligation Analysis • Specifically Tailored for High-Income Earners